Home / Rental Income Tax Calculator
Rental Income Tax Calculator Pakistan 2026-27
A rental income tax calculator shows how much of your rent the tenant must hold back for the Federal Board of Revenue (FBR) and how much reaches your account. For a filer individual landlord in 2026-27, a rent of Rs 100,000 a month attracts Rs 75,000 of withholding a year, or 6.25% overall. The tax follows gross annual rent in four steps, so the rate climbs with the rent.
The slabs are unchanged from 2025-26, according to rate cards and press reports published after the Finance Act 2026. A company landlord pays a flat 15%, and a landlord outside the Active Taxpayers List pays more. Each case below uses the tool’s own code.
How a Rental Income Tax Calculator Works
The calculator multiplies the monthly rent by twelve, finds the slab that holds that annual figure and returns the tax the tenant must hold back. The tax is a fixed amount for the lower steps plus a percentage of the rent inside the current step. The tenant deducts it from each payment, so the monthly tax is the annual tax divided by twelve. Enter the rent, landlord type and your Active Taxpayers List status.
A company landlord pays a flat percentage from the first rupee, and an individual outside the Active Taxpayers List pays more. The slab runs on gross rent, before any repair or other cost. The result is a withholding estimate, as the final tax is settled in your return.
Rent Tax Slabs for 2026-27
A filer individual pays nothing up to Rs 300,000 a year, then 5%, 10% and 25% in steps. The table shows the section 155 rates with the reported non-filer and company treatment. The filer slabs match the tax year 2026 rate card.
Annual gross rent | Filer | Non-filer (reported) |
|---|---|---|
Up to Rs 300,000 | Nil | Nil |
Rs 300,001 to 600,000 | 5% of the amount above Rs 300,000 | Double the filer tax |
Rs 600,001 to 2,000,000 | Rs 15,000 + 10% above Rs 600,000 | Double the filer tax |
Above Rs 2,000,000 | Rs 155,000 + 25% above Rs 2,000,000 | Double the filer tax |
Company landlord | 15% of gross rent | 30% of gross rent |
The jump from 10% to 25% at Rs 2,000,000 a year is the line to watch. Each extra rupee above it loses a quarter to tax. Each rate applies only inside its step.
Section 155: Who Deducts the Tax and Whether It Is Final
Section 155 puts the duty on the tenant, but only when the tenant is a prescribed person. That covers government bodies, companies, non-profits, foreign missions, private schools, clinics and an individual or association of persons (AOP) paying Rs 1,500,000 or more in rent a year. The tenant deposits the tax by the 15th of the next month and should hand over a payment receipt (CPR).
For individual and AOP landlords the tax is an adjustable advance, not a final tax. You declare the gross rent, claim the deduction as a credit and settle the difference in your return. A certificate under section 159 is the route if the withholding would exceed your real liability.
Before You Sign a Tenancy Agreement
Ask whether your tenant is a prescribed person, because only those tenants must deduct. Agree who supplies the payment receipt (CPR) each month. Keep every receipt, because the credit depends on them.
Costs You Can Claim When You File
Deductions do not change the withholding, because the tenant works on gross rent. They reduce the income you declare when you file. Individual landlords can claim a 20% repair allowance without bills (section 15A), so a rent of Rs 1,200,000 a year gives Rs 240,000.
You can also claim property tax and local rates, ground rent, building insurance, collection costs up to 4% of rent and legal costs of defending title. Loan interest counts when the loan financed the property. Keep receipts, except for the repair allowance.
Rental Income Tax Calculator Examples With Interpretation
The four rents below use the tool’s slabs and code. Each is for a filer individual. Each ends with what it means at filing.
A rent of Rs 50,000 a month
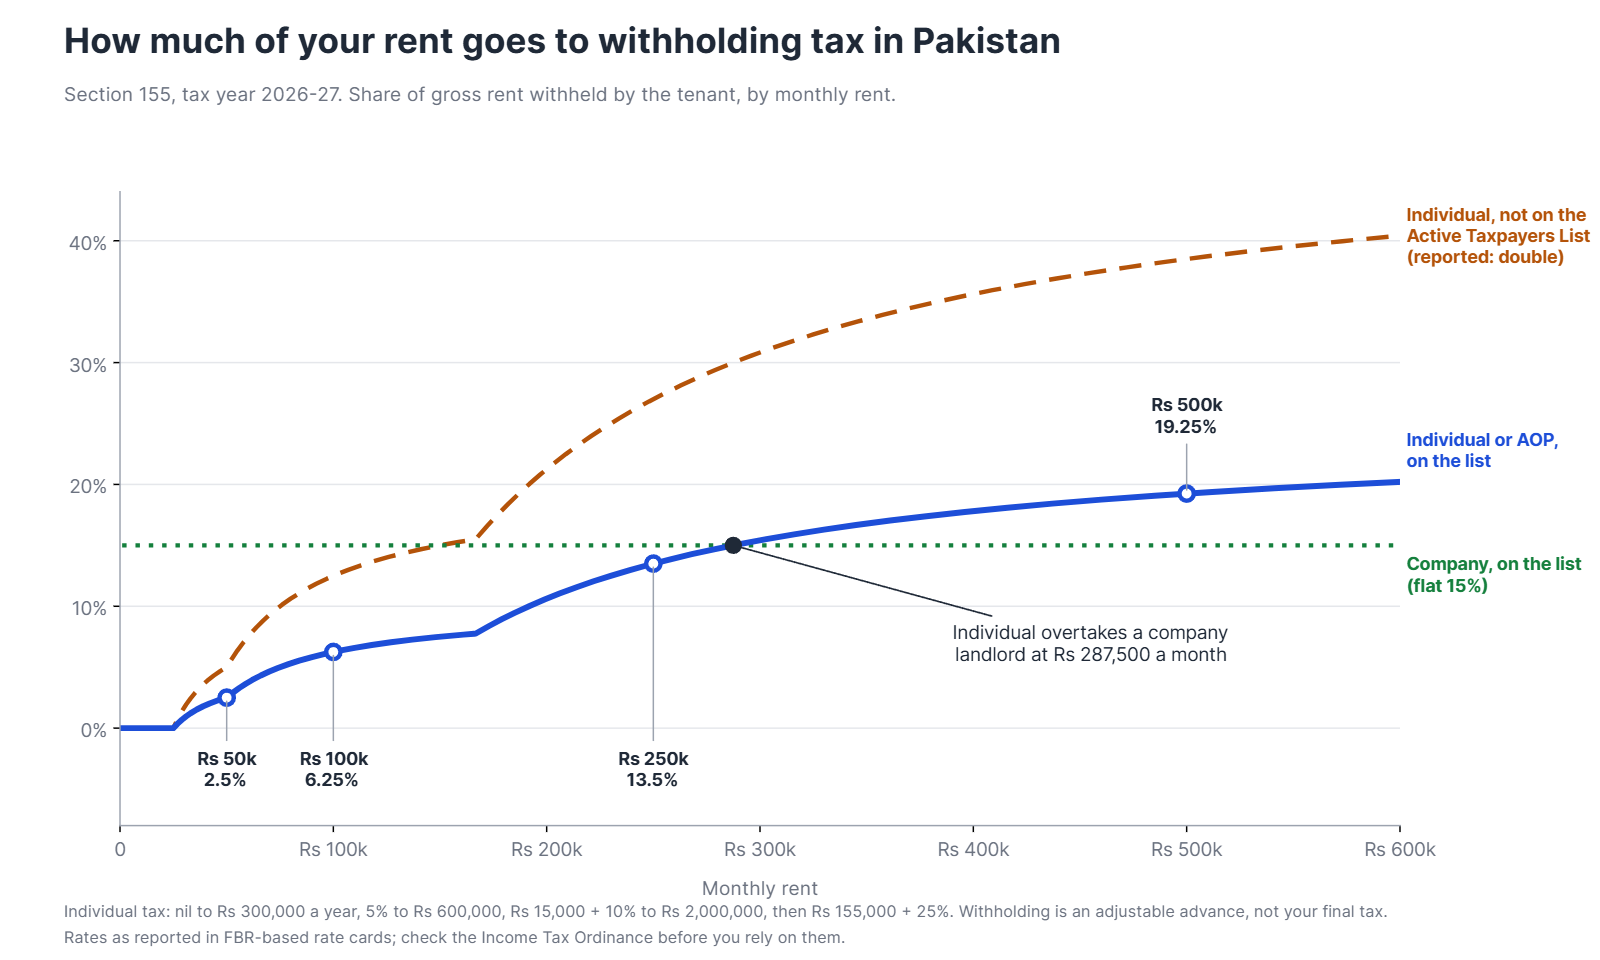
At Rs 50,000 a month a filer individual landlord has Rs 15,000 withheld a year (Rs 1,250 a month), or 2.5% overall. Annual rent is Rs 600,000, so the tax is 5% of Rs 300,000. A private tenant paying under Rs 1,500,000 a year is not a prescribed person, so nothing may be deducted.
A rent of Rs 100,000 a month
At Rs 100,000 a month a filer individual landlord has Rs 75,000 withheld a year (Rs 6,250 a month), or 6.25% overall. Annual rent is Rs 1,200,000, so the tax is Rs 15,000 plus 10% of Rs 600,000. The landlord keeps Rs 93,750 a month; a non-filer is reported to pay Rs 150,000 and a company landlord Rs 180,000.
A rent of Rs 250,000 a month
At Rs 250,000 a month the withholding is Rs 405,000 a year (Rs 33,750 a month), or 13.5% overall. Annual rent is Rs 3,000,000, so the top step applies: Rs 155,000 plus 25% of Rs 1,000,000. The Rs 600,000 repair allowance lowers the income you finally pay tax on.
A rent of Rs 500,000 a month
At Rs 500,000 a month the withholding is Rs 1,155,000 a year (Rs 96,250 a month), or 19.25% overall. Annual rent is Rs 6,000,000, so the tax is Rs 155,000 plus 25% of Rs 4,000,000. Compare final tax on the income tax slabs, not withholding, before you change how you hold the property.
Code Snippets: Rental Income Tax Calculator in JavaScript
This function returns the yearly and monthly tax, the net rent and the repair allowance. The slabs sit in one array, so a rate change is a one-line edit. It mirrors the tool’s constants.
The active flag doubles the individual tax, following the 100% increase that consultant sources report. The output is a withholding estimate. It is not your final return.
// Section 155 rent withholding, tax year 2027 (2026-27), individual/AOP and company landlords.
// [upper limit of annual gross rent, fixed tax, rate on the part above the previous limit]
const SLABS = [
  [300000, 0, 0],
  [600000, 0, 0.05],
  [2000000, 15000, 0.10],
  [Infinity, 155000, 0.25],
];
const FLOORS = [0, 300000, 600000, 2000000];
const COMPANY = { active: 0.15, inactive: 0.30 };
const rs = (n) => Math.round(n);

function rentTax({ monthlyRent, landlord = "individual", active = true }) {
  const annual = monthlyRent * 12;                       // slabs run on gross annual rent
  let tax;
  if (landlord === "company") {
    tax = annual * (active ? COMPANY.active : COMPANY.inactive);
  } else {
    const i = SLABS.findIndex(([max]) => annual <= max);
    const [, fixed, rate] = SLABS[i];
    tax = fixed + rate * (annual - FLOORS[i]);
    if (!active) tax *= 2;                               // "increased by 100%" for inactive taxpayers (reported)
  }
  const repairAllowance = landlord === "company" ? 0 : annual * 0.20; // section 15A, claimed at filing
  return {
    annualRent: rs(annual),
    taxYearly: rs(tax),
    taxMonthly: rs(tax / 12),
    netMonthly: rs((annual - tax) / 12),
    effectivePct: annual ? Math.round((tax / annual) * 10000) / 100 : 0,
    repairAllowance: rs(repairAllowance),
  };
}
// rentTax({ monthlyRent: 100000 }) -> taxYearly 75000, effectivePct 6.25
Security: Tenant Deductions and Fake Certificates
Ignore agents who promise to cut your withholding for a fee, and never share your FBR IRIS login. A lawful reduction comes only from a certificate that the Commissioner issues under section 159. Ask for the CPR each month.
Check the deposit on IRIS before you claim the credit, because tenants sometimes deduct and never deposit. A missing receipt is the warning sign. Name the NTN the deposit must carry.
Common Rental Income Tax Calculator Errors and Fixes
Gaps between your figure and the tenant’s deduction usually come from the base, the status or the tenant type. The table lists causes and fixes. Check a disagreeing figure against these rows first.
Symptom | Likely cause | What to do |
|---|---|---|
Tax deducted on rent under Rs 300,000 a year | Monthly rent read as annual | Ask for the computation and request a nil certificate |
Deduction is double the table | Tenant treats you as off the Active Taxpayers List | Check your status and ask for a recompute |
Tax worked on net rent | Repair allowance applied at source | Claim costs when you file |
Credit missing in the return | No receipt, or a deposit under another NTN | Match the deposit on IRIS first |
If the figure still differs, ask which rate card the tenant used. A deduction only matches a calculation on the same table. Keep the receipts.
Rental Income Tax Calculator Results by Landlord Type
The landlord’s status sets the rate before the rent does. The table applies Rs 100,000 a month to each case. All four are adjustable advances.
Landlord | Rate | Tax on Rs 1,200,000 | Effective rate |
|---|---|---|---|
Individual or AOP, filer | Slabs | Rs 75,000 | 6.25% |
Individual or AOP, non-filer | Slabs doubled (reported) | Rs 150,000 | 12.5% |
Company, filer | 15% flat | Rs 180,000 | 15% |
Company, non-filer | 30% flat | Rs 360,000 | 30% |
An individual’s rate starts low and rises, while a company’s is flat. The two cross at about Rs 3,450,000 a year, or Rs 287,500 a month. Below that the individual route withholds less.
Rental Income Tax Calculator FAQs
These answers cover thresholds, non-filer rates and final-tax rules. Each follows the section 155 slabs above. Your Active Taxpayers List status changes most figures.
Conclusion
A rental income tax calculator should run the slab on gross annual rent, apply the filer or non-filer rule and show the monthly deduction. For a filer individual earning Rs 100,000 a month the answer is Rs 75,000 a year. Pick the landlord type first, because a company landlord pays a flat 15% from the first rupee.
The withholding is only an advance, so file your return with the receipts and claim every allowed cost. Recheck the slabs after each budget. For tax on buying or selling a property, use the FBR property tax calculator, or browse all Pakistan tax calculators.
Official sources
These sources set the rates. Check them against the live pages. The Ordinance and the Act are binding.